US Inflation Climbs to 3.7% Ahead of Midterms as Gasoline Prices Surge
US consumer prices rose faster than economists had anticipated last month, with annual inflation reaching 3.7% in September, according to official figures released on 14 October 20
US consumer prices rose faster than economists had anticipated last month, with annual inflation reaching 3.7% in September, according to official figures released on 14 October 2026. The uptick marks a notable acceleration from the 3.4% rate recorded in the twelve months to August and represents the final inflation reading before voters head to the polls in next month's midterm elections.
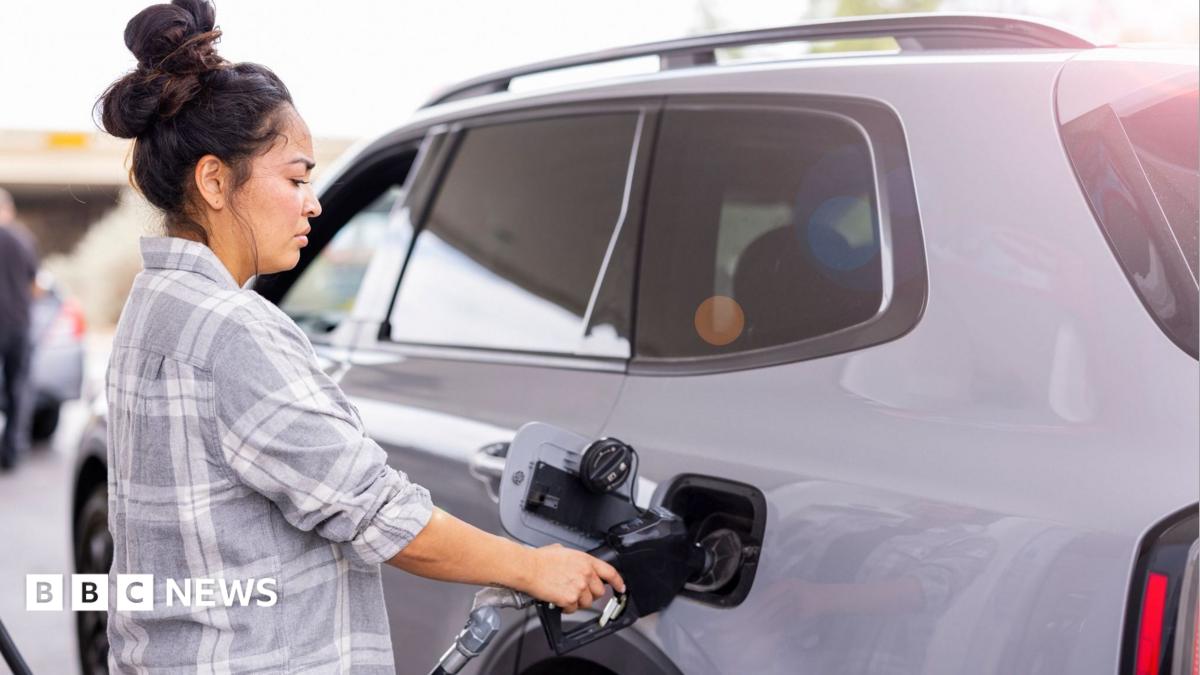
The Bureau of Labor Statistics, which compiles the monthly consumer price index, reported that the pace of price increases exceeded forecasts. The surprise uptick was largely attributed to a sharp rise in gasoline costs, which have climbed following disruptions to energy supplies from the Middle East linked to the US-Israel conflict with Iran. With cost of living pressures dominating the political agenda, the data lands at a sensitive moment for the administration and for candidates on both sides of the aisle.
Inflation itself is the rate at which the prices of goods and services rise over time. A simple illustration: if a bottle of milk costs $1 and then sells for $1.10 a year later, the annual inflation rate for that item is 10%. The Bureau of Labor Statistics tracks this by monitoring the consumer price index, which measures price changes across hundreds of everyday items, including fresh food, gasoline and medical services. The basket of goods is periodically updated to reflect shifts in spending patterns and lifestyles.
Several forces can push inflation upward. When demand for a product exceeds available supply, producers may respond by raising prices. Higher household incomes can also fuel demand and, in turn, drive prices higher. Supply-side shocks matter just as much. When the supply of a commodity falls while demand holds steady, prices typically climb. Crude oil, the raw material behind gasoline and diesel, is a prime example. Before the US-Israel war with Iran began, a barrel was trading at just over $70, but as the conflict constricted supplies, the price surged past $100.
The September figures show inflation running at 3.7% year-on-year, an increase driven chiefly by fuel costs. Car fuel prices jumped by 34.2% over the twelve-month period. In September alone, they rose by 9.1%, accounting for more than half of the overall increase in inflation, according to the Bureau of Labor Statistics. Energy inflation more broadly was up 20.4% over the year, as prices for fuel oil, energy services and electricity all climbed. Fuel oil, which is used for home heating, registered a striking 74.2% annual increase.
Analysts noted that the Federal Reserve, which sets the country's interest rate, will be monitoring closely whether energy costs begin to spill over into other parts of the economy, such as food prices, and push inflation even higher. For now, food inflation remains comparatively contained. It was flat over the month of September and stood at 2.5% across the year. Core inflation, which excludes the volatile food and energy categories, came in at 2.6%.
The release had immediate consequences for government benefits. Shortly after the inflation figure was published, the Social Security Administration announced that payments including old age, survivors and disability insurance would rise by 3.6% in 2027. Officials said the adjustment would translate into an average retirement benefit increase of $75 a month. The cost of living adjustment takes effect in January for roughly 72 million people, while increased payments for the 7.2 million recipients of supplemental security income will begin on 31 December.
Trade policy has also played a role in the price picture. Since returning to office for a second term, President Donald Trump has introduced tariffs on most US trading partners. Although the Supreme Court struck down most of the additional global levies in February, the president immediately announced a new 10% global tariff to replace them. Trump has argued that the tariffs would boost America's tax earnings, strengthen manufacturing and encourage consumers to buy US-made goods.
However, research from the Federal Reserve Bank of New York suggests the import taxes have fed into inflation. Tariffs are levies that businesses pay on imported goods, and they directly raise costs for US companies unless overseas suppliers lower their prices to absorb some of the burden. The New York Fed found that exporters reduced prices very little in response, meaning US-based businesses ended up absorbing nearly 90% of the added tax.
The effects were not confined to imported goods. Higher tariffs also influenced the prices of domestically made products, since many US producers depend on parts or materials sourced from abroad. On aggregate, the Fed estimated that every percentage point increase in average tariffs led to roughly a 0.25% rise in consumer goods prices after one year. That pass-through effect helps explain why tariff policy has become entangled with the broader inflation debate.
While the current rate sits above the Federal Reserve's 2% target, it remains well below the peaks seen in previous years. The central bank has consistently signalled that it wants to see inflation return to its target before adjusting interest rate policy, though it must also weigh signs of economic slowing. Persistent energy-driven inflation could complicate that calculus, especially if higher fuel costs start to filter into transport, food and other essentials.
For ordinary Americans, the practical effect is felt at the pump and in the weekly grocery shop, and the political stakes are considerable. The midterm elections are being fought squarely over cost of living pressures across the country, and the latest data gives both parties fresh ammunition. Candidates will likely spar over whether tariffs, energy policy or global conflicts bear the greatest responsibility for the squeeze on household budgets.
Economists caution that a single month of elevated inflation does not necessarily signal a lasting trend, particularly when the spike is concentrated in one volatile category such as gasoline. Much will depend on whether the Middle East supply disruption eases and whether energy costs begin to bleed into core prices. The Federal Reserve's next moves, the trajectory of the conflict with Iran, and the durability of tariff policy will all shape whether inflation cools in the months ahead or continues to climb.
What's Your Reaction?
 Like
0
 Dislike
0
 Love
0
 Funny
0
 Wow
0
 Sad
0
 Angry
0
Fact-Check Editor. Verifikator bersertifikasi IFCN. Memeriksa klaim viral dan disinformasi.


Comments (0)